<
Estate Planning

Guidance for those who follow

Wildflowers in yellow, pink, red, and purple in front of a brick building with white-trimmed windows.
Icons showing airplane, shoe, bed, Wi-Fi, energy, bulb, car, cloud, shield, and user profile in black and white.

The questions are answered before anyone has to ask.

Estate planning is the work of leaving clear instructions in the right places. Wills, trusts, beneficiary designations, executor choices, healthcare directives, and the tax math behind each transfer all have to point the same way.

We coordinate the documents, the titling, and the beneficiary designations across the estate. Tax positioning, transfer timing, and alignment with retirement and investment accounts all get worked together. The plan stays current as the assets move, the family changes, and the law evolves.

No question left unanswered

Painting showing a glass carafe and a goblet with water on a table by a window, in a decorative frame.

Documents that agree

Woman in glasses and white sweater standing by a window in a dimly lit bar with pink stools.

Titles and beneficiaries that match

Top view of a spiral staircase surrounding a green garden, with a person reaching toward the plants.

Tax-aware transfers

Wildflower meadow with pink, yellow, and red flowers in front of an old brick building.

Coordinated with your attorney

The will, the revocable trust, any irrevocable trusts, the durable power of attorney, and the healthcare directive all have to read like one decision. When they conflict, the family inherits the conflict.

Beneficiary designations on retirement accounts and life insurance overrule the will. Asset titles — whether joint, sole, or trust-owned — determine what passes outside the estate. These have to line up with the rest of the plan, or the rest of the plan doesn't matter.

Estate tax exemptions span multiple years rather than collapsing at the end. Step-up basis gets preserved where it matters, generation-skipping exemptions reach the right beneficiaries, and gift-tax annual exclusions get used while they're available.

Estate documents are drafted by an estate attorney. We coordinate everything else: the titling of every account, the beneficiary designations on retirement and insurance, the tax positioning across transfers, the executor and trustee structures, and the family conversations when they're needed.
How the work happens

01
First conversation
02
The full picture
03
Bringing the picture together
04
Putting it to work
05
Through every change

01

First conversation

Before any document review, there's a real conversation about what brought you here. Often it's a new baby, kids reaching adulthood, an aging parent, a business sale on the horizon, a remarriage, or documents that haven't been touched since the kids were small. By the end you'll know whether this fits and what working together involves.

Two people at a table with one reading a book, the other holding a cup, muffins and plant nearby.

02

The full picture

Most estate planning starts with what's already in place: documents signed years ago, trusts that exist on paper but never got funded, beneficiary forms still showing an ex-spouse or a deceased parent, or asset titles that don't match what the will assumes.

03

Bringing the picture together

The plan gets built across documents, asset titling, beneficiary designations, and tax positioning together. The attorney handles drafting; the rest happens here. Trade-offs surface explicitly: gifting now to use exemption or holding for step-up later, trusts to control timing or outright bequests, joint ownership for convenience or trust ownership for protection.

04

Putting it to work

Documents get signed and stored. Beneficiary forms get filed with every account that needs an update. Asset titles change where the plan requires. Trusts receive the assets they were structured to own.

Person typing on a laptop at a wooden table with plants and glass in a cozy room.

05

Through every change

Estate plans go stale in two ways. Life changes the picture: marriage, divorce, birth, death of a spouse, sale of a business, a child becoming a parent themselves. Or, law changes the math: exemption thresholds, gift-tax limits, state-level estate tax adoption or repeal. Each one reopens specific decisions in the plan.

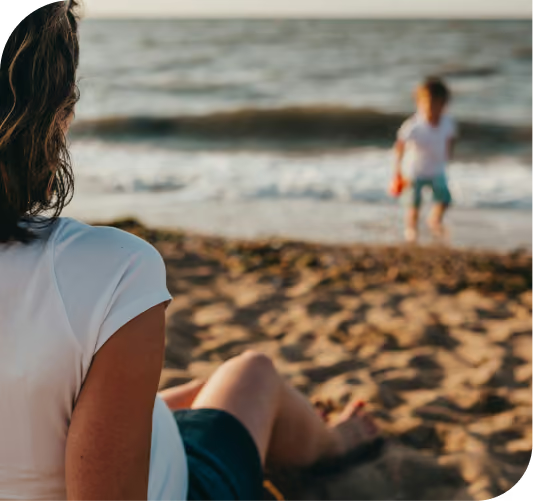
Woman sitting on sandy beach watching a child standing near the water's edge with waves in background.

The advisor who builds your estate plan is the advisor your family already knows.
Estate planning is the relationship that lives longest. The senior advisor who built the plan knows the family, the assets, and the intent behind every decision. When the moment arrives, no one is meeting a stranger.

Our advisors keep concentrated client books so the senior advisor stays close to the family across every revision the plan needs. When a decision crosses into tax, investments, or retirement, the specialists are in-house and one conversation away.

Redondo Beach, CA
Rob Santos
CEO

Rob works with founders, executives, and families navigating concentrated wealth, business exits, and generational planning. He founded Arrowroot in 2013 and leads the firm from Southern California.

CONNECT WITH ROB
El Dorado Hills, CA
Cassandra Barry
Managing Director

Cassandra works with clients on retirement planning and Medicare strategy, with deep expertise in healthcare cost planning and the tradeoffs that shape later-life decisions. She is a licensed insurance agent with more than 12 years in financial services.

CONNECT WITH ROB
Gig Harbor, WA
Crystal McMahon, CFP®, EA
Managing Director

Crystal works with individuals, families, and business owners on financial planning, investment management, and tax strategy. She is a CFP® and IRS Enrolled Agent with over two decades of experience.

CONNECT WITH ROB
Denver, CO
Irene Apergis
COO

Irene oversees operations and regulatory compliance across the firm. She brings more than 22 years of financial services experience across investments, capital markets, operations, management, and sales.

CONNECT WITH ROB
Charlottesville, VA
Mark McCarron, CFP®, EA
Partner, Managing Director

Mark works with families and business owners on financial planning, portfolio management, and tax strategy, with a particular focus on cash flow and long-range projections. He is a CFP® and IRS Enrolled Agent.

CONNECT WITH ROB
Rochester Hills, MI
Diane Young, AIF®
Partner, Managing Director

Diane works with individuals, families, executives, and retirees on retirement planning, investment strategy, and long-term wealth management. She is an Accredited Investment Fiduciary® with over 30 years of experience.

CONNECT WITH ROB

How it all connects

Business Owner Planning

Tax Planning

Investment Management

Insurance

Icon of a sheet of paper with a folded corner and a checkmark on it.

Retirement Planning

Financial Planning

Equity Compensation

Estate Planning

Stacked coins and a city skyline overlaid with financial charts and data.

Business Owner Planning

Building a business creates a personal wealth situation the business itself won't manage. Concentration in the company, deferred compensation, an eventual exit, and the retirement that follows each carry their own math. Decisions on the company side get coordinated with the personal plan so the two sides move together.  

Explore Business Owner Planning
Grid of white dots arranged in eight rows and five columns on a black background.

Tax Planning

Threads through every investment decision and every estate document. Tax efficiency depends on timing as much as choice. Decisions get made so the math holds up across decades rather than quarters.

Explore Tax Planning
Grid of white dots arranged in eight rows and five columns on a black background.

Investment Management

Built around the obligations the portfolio has to meet. Holdings fund retirement income, education, gifting, and the unexpected on schedules that match real life. Risk gets calibrated to the work, and tax planning runs through every position.

Explore Investment Management
Grid of white dots arranged in eight rows and five columns on a black background.

Retirement Planning

At the center of cash flow, tax, and investment decisions, this long phase has its own math at every stage. Income, taxes, and sequence get modeled so the timeline holds up under stress. The work continues across every transition retirement contains, since one phase rarely sets the pattern for the next.

Explore Retirement Planning
Grid of white dots arranged in eight rows and five columns on a black background.

Estate Planning

Touches every other practice the moment something changes. Estate, tax, and investment positions stay aligned so the structures still work when the time comes. Documents get revisited as the family and the assets shift.

Explore Estate Planning
Grid of white dots arranged in eight rows and five columns on a black background.

Insurance

Protects what's been built when something happens. Coverage gets sized to real exposure across business interests, dependents, and estate liquidity. As obligations shift, coverage shifts with them so the protection matches the situation.

Explore Insurance
Grid of white dots arranged in eight rows and five columns on a black background.

Equity Compensation

Stock from your employer carries three identities at once: a tax position, an investment position, and a concentration risk. Vesting, exercise, sale, and AMT decisions get weighed together rather than separately. Timing of each gets coordinated against the broader picture.

Explore Equity Compensation
Grid of white dots arranged in eight rows and five columns on a black background.

Financial Planning

Financial Planning is the practice that integrates the others into one plan. Tax decisions get made with investments in view, estate work gets shaped by the cash flow strategy, equity compensation gets calibrated against the rest of the picture. The plan holds together because one advisor guides it.

Explore Financial planning
Grid of white dots arranged in eight rows and five columns on a black background.

Let’s get started

Tell us where you are, where you're headed, and what you're working with. We'll help you get there.

Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.